Content


Mobile Marketing Specialist

Copywriter at Promodo
Over nearly three years as a copywriter, I’ve written for US and European startups and companies, including SE Ranking. I enjoy working with words—finding the right phrasing, organizing ideas, and turning them into clear and useful content that shows real value and helps businesses grow.
Worldwide, fintech growth is no longer coming from new downloads: finance app installs are falling while sessions keep growing. That changes which metrics are worth tracking.
Together with mobile marketing specialist Yana Afanasieva, we looked at the fintech marketing benchmarks and trends that matter most in 2026.
This report combines 2025–2026 data from Adjust, AppsFlyer, Singular, CleverTap, J.P. Morgan, WordStream, Brevo, Conductor, Cornerstone Advisors and others, and Promodo’s own benchmark data.
In 2025, global fintech app downloads fell 4%, while sessions grew 21% and Finance category revenue rose 10.2% (Adjust, Singular). Over the same period, the global fintech CPI dropped from $1.51 to $1.13.
Global fintech is getting cheaper to buy traffic for and better at monetizing it. The category is already saturated with apps, so growth comes less from new installs and more from deeper engagement of existing users.
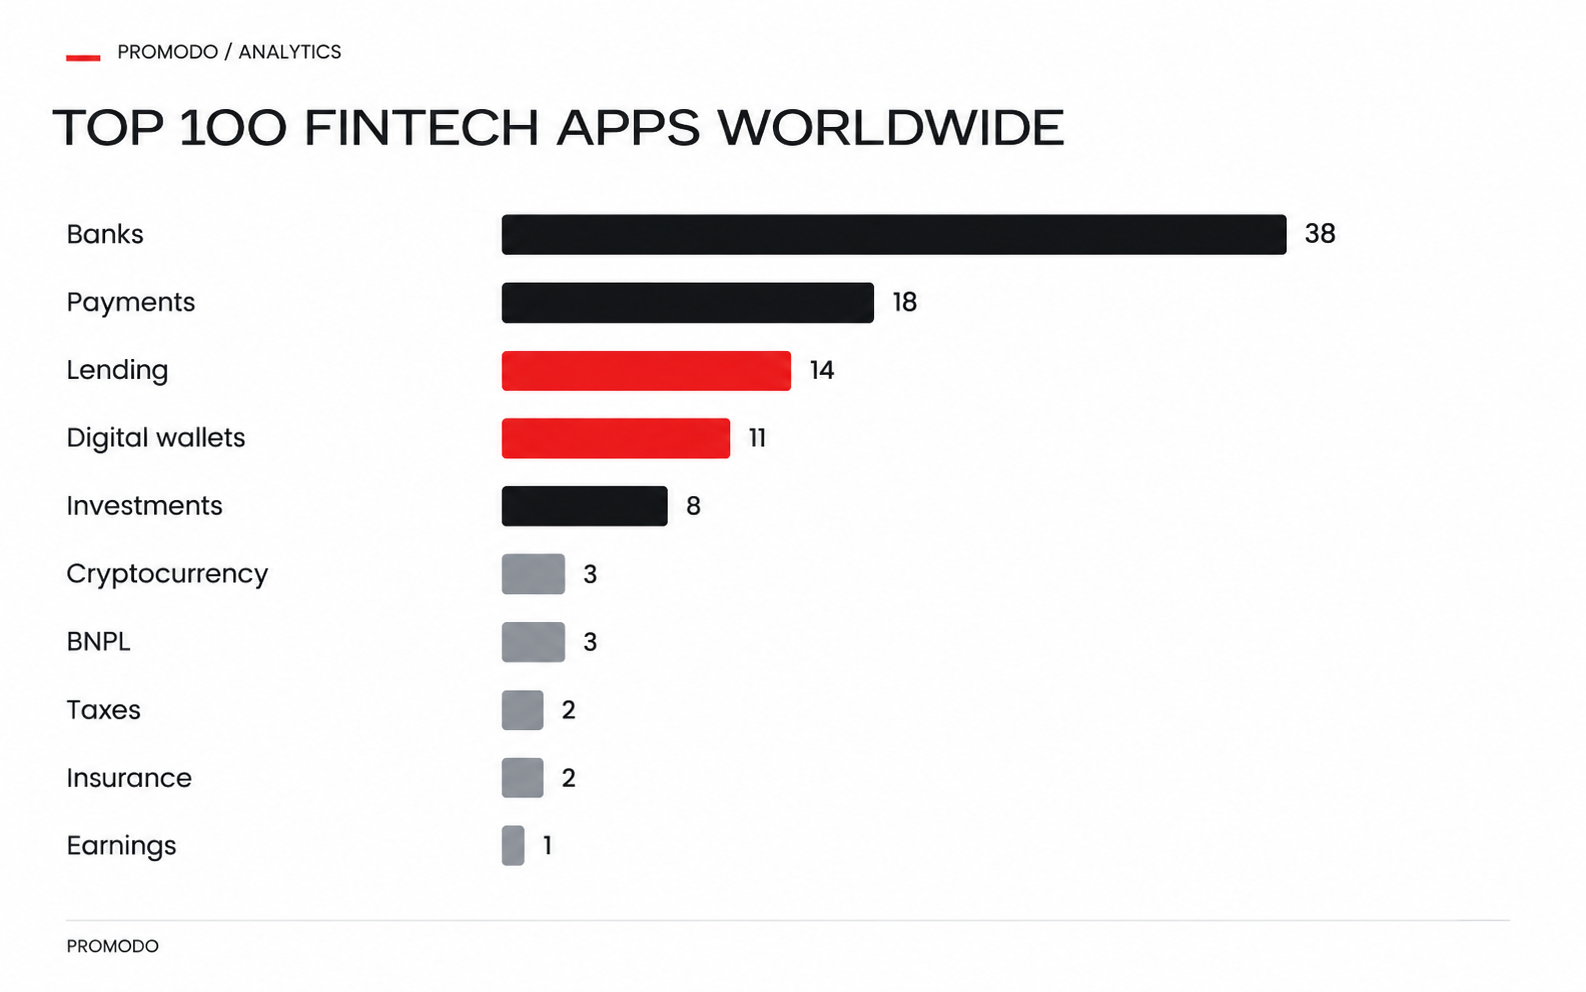
Of the rest. 18 are payment apps, 14 are lending apps, 11 are digital wallets, and 8 are investing apps.
Lending is growing fastest: from 5 to 14 apps in the top 100, mostly because of India. Digital wallets rose from 4 to 11. In South Asia and Africa, mobile money has replaced the bank altogether.
By contrast, crypto apps fell from 15 to 3. Activity has shifted to payment infrastructure and stablecoins.
In 2025, fintech app sessions grew faster than installs in most regions:
Source: Adjust
Installs are still growing faster than sessions in Latin America (+76% vs +57%) and APAC (+50% vs +5%).
On average, a fintech app install costs $1.13, but subcategories vary widely. Banking has one of the priciest installs (only crypto costs more), yet it also keeps users best. Payments is the only subcategory where CPI went up over the year. Crypto went the other way: CPI dropped from $5.17 to $2.90 as competition cooled.
Sources: Adjust, Mobile app trends 2026; Adjust, The finance app insights report 2025
The global average hides large regional gaps. In Europe, a finance app install costs $4.75, and in North America $4.13. Both are down sharply from 2024, but still roughly four times the global $1.13. The global figure is pulled down by high-volume, low-cost markets.
Source: Adjust
Cheap installs aren’t always real ones. AppsFlyer found that in Western Europe, nearly one in every two installs in investment apps was flagged as fraudulent, well above banking and digital wallet apps. Cost per install only means something when the installs are real users.
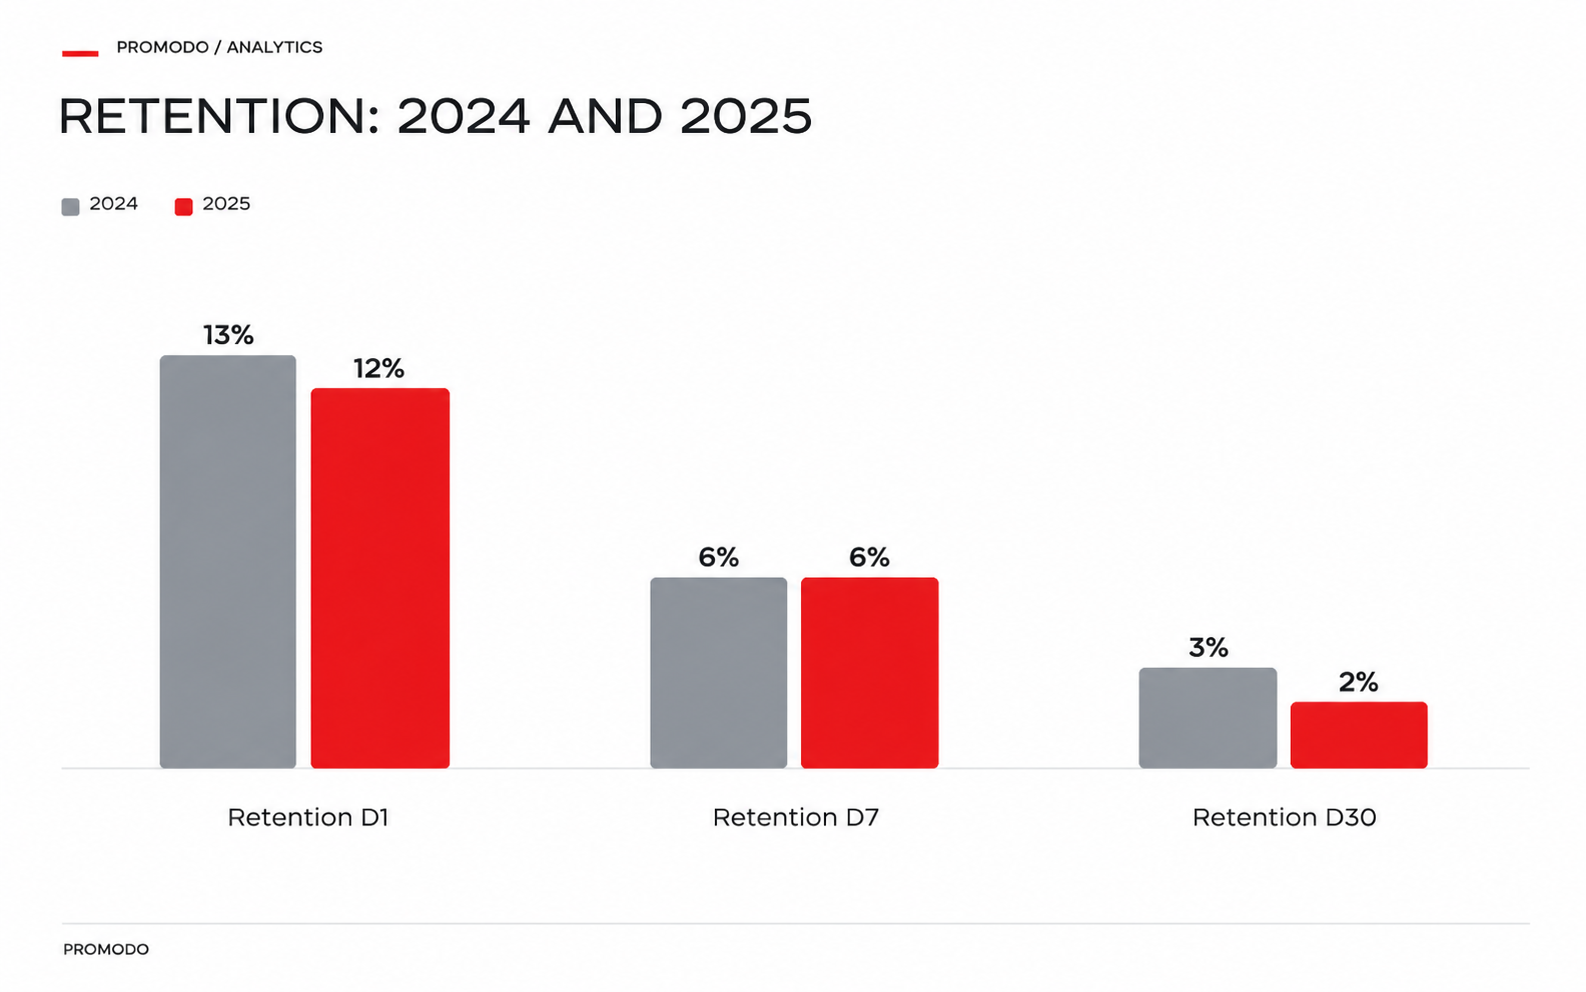
According to Adjust, fintech retention in 2025 was 12% on day 1, 6% on day 7, and 2% on day 30. Banking apps retain 20.6% of users on day 1. That’s the highest of any fintech subcategory and 8 percentage points above the category average.
The average session in a fintech app lasts 7.18 minutes, 8% longer than a year ago.
North America sessions run longer than the global average: 8.43 minutes versus 7.18, according to Adjust.
Europe shows how much the business model matters. According to AppsFlyer, traditional banks retain users on day 30 at 1.5 to 2 times the rate of neobanks.
In our mobile marketing benchmarks, finance apps keep 12% of users on day 1 and 2% on day 30 according to Adjust, while Getstream’s category data shows 26.84% and 8.03%. The sources use different data and methods, so pick one and compare your own numbers against it consistently.
We also looked at stickiness there. Financial services apps typically have a DAU/MAU ratio of 10–20% (KPI Tree), and fintech and eCommerce apps 15–30% (Kissmetrics).
Meanwhile, paid traffic now outweighs organic: the paid-to-organic ratio in fintech is 1.13. Organic no longer drives growth on its own. iOS tracking consent (ATT opt-in) is slowly rising and now stands at 38% (Adjust), but it remains low in finance, which hurts attribution.
That doesn’t make store visibility any less important. When we worked with monobank, a branchless neobank with 9.6 million clients, the app already had strong ASO and stable visibility, so the goal was to push further: more visibility in the stores, more organic downloads, and more of the target audience turning into customers.
We built a new semantic core, grouping keywords by popularity and competitiveness, and updated the title, subtitle, and description in both stores. On the App Store, we launched In-App Events to showcase new products and features, a tool no other fintech & banking company had used before. Google and Facebook campaigns ran alongside to build daily download momentum, which supports store rankings.
The result: downloads grew by 15%, and the app reached top positions in the Finance category on both the App Store and Google Play.
The global numbers blend very different markets. If you buy traffic in the US or Europe, the more useful picture starts after the install: search, AI answers, onboarding and email.
Plenty of fintech journeys start on the web rather than in the store. In Western Europe, web-to-app is the largest owned-media channel in finance, responsible for 41.8% of owned-media conversions (AppsFlyer). For US search advertisers, the closest category to fintech is Finance & Insurance, and the 2026 benchmarks from WordStream show a familiar pattern: people click, but few convert.
Clicks in finance are cheap: a click costs $3.39, which is 37% less than the all-industry median of $5.42. The problem is what happens next. Only 2.64% of clicks convert, against 8.18% across industries, so a lead still costs $74.44 instead of $66.69. Lowering your bids is rarely the answer. The problem usually lies in landing pages, eligibility checks and application flows. Keep in mind that these are US medians, so they may not hold for Europe.
Finance is one of the hardest niches to appear in when people ask AI for recommendations. In Promodo’s GEO benchmarks, based on GELIOS data, Finance has an AI Visibility of 6.2%, which means AI mentions a brand in only about one in sixteen queries. That sits in the “weak” band (under 10%) and far below the 19.9% median across the 19 industries we track. A typical answer names just 1.9 brands, and the average brand holds a 4.8% Share of Voice, while the leader reaches 11.9%, about 2.5 times the average. The Finance numbers come from 371 AI responses.
Traffic is a different story. Conductor’s benchmarks for US Financials show Google AI Overviews on 25.8% of queries. Yet AI platforms sent only 0.48% of site traffic, and ChatGPT was behind 89.7% of those visits. For now, AI search in finance is a visibility play more than a traffic channel.
Banking shows a similar pattern. Most digital account applications are never completed. According to a 2026 Cornerstone Advisors report, 27% of new checking accounts at US banks and credit unions were opened digitally last year. But for every digital application that was completed, 3.36 were abandoned, which works out to a completion rate of about 23%. Fraud controls also rejected roughly one in four applications.
The causes are familiar: forced offline steps like document uploads, sessions that don’t carry over between devices, and identity-verification delays. The data covers banks and credit unions, not neobanks.
Email is another inexpensive engagement channel. Brevo gives Banking & Financial Services a 21.30% open rate and a 1.87% click rate, just below the 2.27% all-industry average. Across all industries, Europe outperforms North America on both opens and clicks. Apple Mail Privacy Protection inflates open rates, so compare your own data with the first row of the table, not the second.
Triggered emails perform about twice as well as promo emails. According to Promodo’s email benchmarks, the average conversion rate across industries is about 1% for promo campaigns and about 2% for triggered emails, which makes onboarding and re-engagement flows the natural place to start.
Judging a campaign by installs alone isn’t enough. What matters is how many users go further: register, activate, and become customers.
Only 1 in 5 users who install a fintech app registers within the first week according to Clevertap reports. And according to First Page Sage, the average customer acquisition cost in fintech is $202.
At the same time, push notifications remain an inexpensive engagement channel, with a CTR of 9% on Android and 6% on iOS.

[[FAQ-START]]
Across finance apps, Adjust reports a CPI of $1.13, a CPC of $0.19, a CPM of $2.76 and a CTR of 2.0%. Subcategories differ: banking has a CPI of $2.09, payments $1.44 and crypto $2.90. Banking installs are among the priciest (only crypto costs more), but banking apps also retain users best.
Adjust’s 2025 data shows fintech apps keep 12% of users on day 1, 6% on day 7 and 2% on day 30. Banking apps lead with 20.6% on day 1, about 8 percentage points above the category average. Payments apps retain 17.7% and crypto 15.7% on day 1.
Globally, no. In 2025, fintech installs fell 4% while sessions grew 21% (Adjust). Latin America is the exception, with installs up 76%. In Europe, MENA and North America, sessions grew faster than installs. For marketers, this means growth now comes from engaging existing users, not just from buying more installs.
Lending is growing fastest, from 5 to 14 apps in the global top 100, mostly because of India (Singular). Digital wallets rose from 4 to 11, while crypto fell from 15 to 3. Banks are still the largest group, with 38 apps.
[[FAQ-END]]
Mobile Marketing Specialist
Copywriter at Promodo
Over nearly three years as a copywriter, I’ve written for US and European startups and companies, including SE Ranking. I enjoy working with words—finding the right phrasing, organizing ideas, and turning them into clear and useful content that shows real value and helps businesses grow.
You may also like
Choose quality and trusted services to improve the presence of your company on the Internet, and feel free to contact our UK team if you have any questions.
Changing a website’s domain has always been — and will remain — a risky process for any site.

According to the most recent pet industry statistics, American pet owners alone spend more than $103 b. on pet care products.
In this article, we’ll share the key SEO KPI metrics that help you evaluate search performance end to end.
We at Promodo are ready to help you improve your performance across all digital marketing channels.
Get started